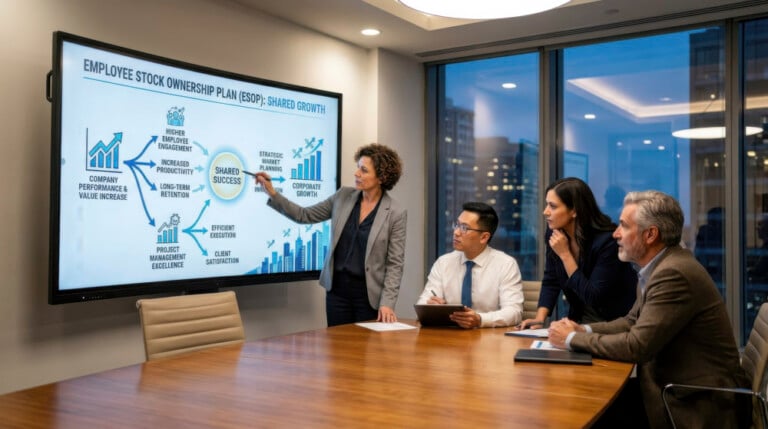
After years of building a business, it is common for owners to seek an exit strategy that preserves the culture and rewards the employees who helped make the business successful. An employee stock ownership plan, or ESOP, is one way to accomplish that goal.
While the benefits of an ESOP can be significant, the transition also introduces important wealth management considerations for everyone involved. Whether a business owner or employee, here are some points to keep in mind.
When a business transitions to an ESOP, the owner receives payment for their stake, while employees gain a pathway to ownership through shares held in the ESOP trust. For many owners, this may be one of the largest liquidity, and wealth-generating, events of their lives. That makes wealth management planning critical. The business owner should retain experienced advisors who understand tax concerns and can help to ensure tax benefits are not lost and that proceeds are invested correctly.
A wealth advisor and financial planner can help business owners evaluate how to construct an optimal estate plan and investment portfolio for their next chapter. That planning should include investment management, retirement savings, estate planning, philanthropic giving or perhaps a new business venture. The goal is to help create a plan that reflects the owner’s long-term objectives and legacy.
Business owners considering any kind of business sale, such as through an ESOP, should begin estate planning as early as possible and well before the transaction is finalized. A coordinated advisory team, including a lawyer, financial planner and accountant, can help evaluate the appropriate strategies based on the owner’s goals. For example, if a sale is expected to generate a large capital gain, some owners may consider charitable planning vehicles, such as a charitable remainder trust, for a portion of the business interest. This can provide an income stream while also supporting charitable goals and potentially reducing the immediate tax impact.
These strategies are complex and not appropriate for every situation, which is why owners should work closely with qualified tax, legal and wealth advisors to understand their options and create a plan reflecting their goals.
An ESOP is a retirement plan, which means employees should think about it as part of their broader financial picture.
In most cases, employees receive shares of the company over time based on the terms of the plan. If the company continues to grow and performs well, the value of those shares may increase. This means employees have a direct interest in the company’s continued success. At the same time, employees should understand how ESOP benefits fit with other retirement savings, such as a 401(k), IRA or personal investment account.
Important questions for employees may include: When will I become eligible to participate in the ESOP? How are shares allocated?
When do I become vested? What happens if I leave the company before retirement? How and when can I access the value of my shares? What are the tax implications of taking a distribution? How does this fit into my overall retirement plan?
Retirement age is especially important. Depending on the plan, accessing ESOP distributions early could result in taxes or penalties. Employees should understand the rules before making decisions about retirement timing, career changes or distributions.
The success of an ESOP depends in part on how the plan is structured. A plan document sets the rules for eligibility, vesting, share allocation, distributions and other key details.
The business owner and company management should consider engaging an attorney to draft the plan document based on guidelines provided by the Internal Revenue Service (IRS) and the ultimate goals of the ESOP.
Because an ESOP is a qualified retirement plan, it requires proper administration and compliance. Businesses should work with experienced advisors, including an ESOP attorney, trustee, valuation expert, CPA and qualified plan administrator, to draft the plan document and help ensure its ongoing qualification with the IRS.
For employees, the plan determines how wealth is accumulated and accessed. For the company, the structure affects cash flow, repurchase obligations and long-term sustainability. The goal is to create a plan that rewards employees while helping the business remain financially strong.
An ESOP can be a powerful tool for business succession, employee engagement and long-term wealth creation. But the transition is only the beginning. Once an ESOP is in place, both owners and employees alike should plan carefully for how to manage, protect and sustain the wealth they created.
With the right planning and guidance, an ESOP can do more than transfer ownership; it can help create a stronger financial future for the business owner, the company and its employees.
Susan Martore-Baker is president of Cambridge Trust Company of NH. The opinions expressed herein are those of the author, and do not necessarily reflect those of Eastern Bankshares, Inc., Eastern Bank or any affiliated entities.